Blog
Critical Illness and Disability Insurance: If You Couldn’t Work
A guide to critical illness and disability insurance.
Why it matters
Your ability to earn an income is likely your biggest asset. A serious illness or injury can stop the paycheques, while the bills keep coming.
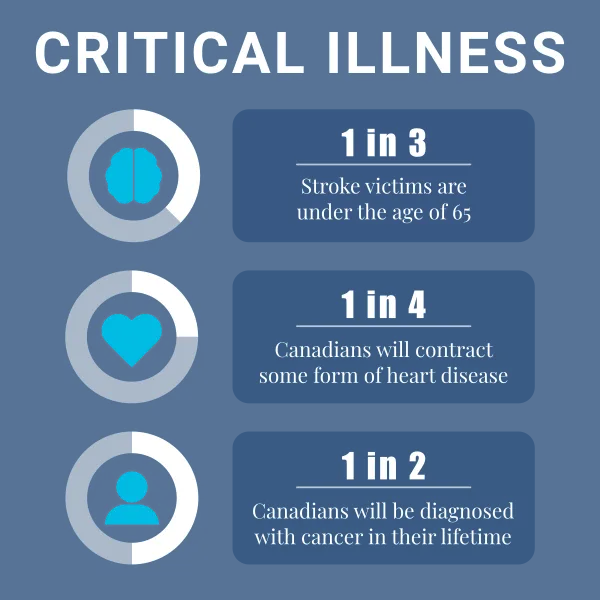
- 2 in 5 Canadians are expected to be diagnosed with cancer in their lifetime.
- 1 in 3 Canadians will be disabled for 90 days or more at least once before age 65.
- 2–3 yrs is the average length of a disability that lasts longer than 90 days.
Sources: Canadian Cancer Society; CLHIA, Guide to Disability Insurance; RBC Insurance.
How each one works
A lump sum
Tax-free cash if you’re diagnosed with a covered illness, such as cancer, heart attack or stroke, and survive the waiting period.
A monthly income
Replaces part of your pay while illness or injury keeps you from working, often until you recover or turn 65.
Both bases covered
Critical illness handles the big one-time costs. Disability keeps the income flowing.
What the money can do
- Pay for care such as treatment, medication and therapy not covered by Medicare.
- Give your family time, so a spouse can take time off to help you recover.
- Keep plans on track: the mortgage, the bills and your savings.
Most people survive a serious illness. That’s the good news. It’s also why the cost of recovery, not just treatment, needs a plan.
Questions to ask
- At work: What’s covered? Do you have group disability? How much, and would benefits be taxable?
- Self-employed: Who pays you? There’s often no employer plan to fall back on if you’re off.
- Waiting period: When does it start? Benefits may begin after 30, 90 or 120 days. Could you wait that long?
- Definition: Which job counts? Does it pay if you can’t do your own job, or only if you can’t do any job?
Options that fit your budget
You don’t need to buy everything at once. Coverage can be built around what matters most to you.
- Return of premium. Some critical illness plans refund your premiums if you never make a claim.
- Coverage for children. Critical illness can be added for your children, often at low cost.
- Flexible terms. Shorter terms or coverage to age 75 keep premiums manageable.
Group plans have limits. Workplace disability coverage usually ends when you leave the job, and benefits may be taxable if your employer pays the premiums.
Getting started checklist
- Check what your workplace plan covers.
- Work out how long your savings would last without a paycheque.
- Decide how much monthly income you’d need.
- Consider a lump sum for treatment and recovery costs.
- Ask about coverage for your children.
- Review coverage when your income changes.
Living benefits, explained
Life insurance pays when you die. These coverages pay while you’re living, when you need help the most.
- Critical illness: Paid once, tax-free, and you decide how to spend it.
- Disability: Paid monthly. Benefits from a policy you pay for yourself are generally tax-free.
Applying, step by step
- Tell me about your work and your health.
- Compare plans from several insurers.
- Apply, answering any medical questions.
- Review your policy together once it’s issued.
Apply while you’re healthy. A change in your health can make coverage harder to get or more expensive. The best time to apply is before you need it.
Let’s protect your income
I’ll help you find where the gaps are and how to close them at a cost that fits.
Book a conversation with Michael, or call the office at 506-406-6100 (cell 506-440-6196). Email: [email protected]. Ask for a printed copy of this brochure at your next meeting.
For general information only; not tax or legal advice. Covered conditions, waiting periods and benefits depend on the policy and the insurer. We’ll review the details that apply to you together.
Location
400-494 Queen St,
Fredericton, NB, E3B 1B6
Office (506) 406-6100
© 2026 Plume Financial